
Fundamental Volatility
Tue, Nov 03, 2026
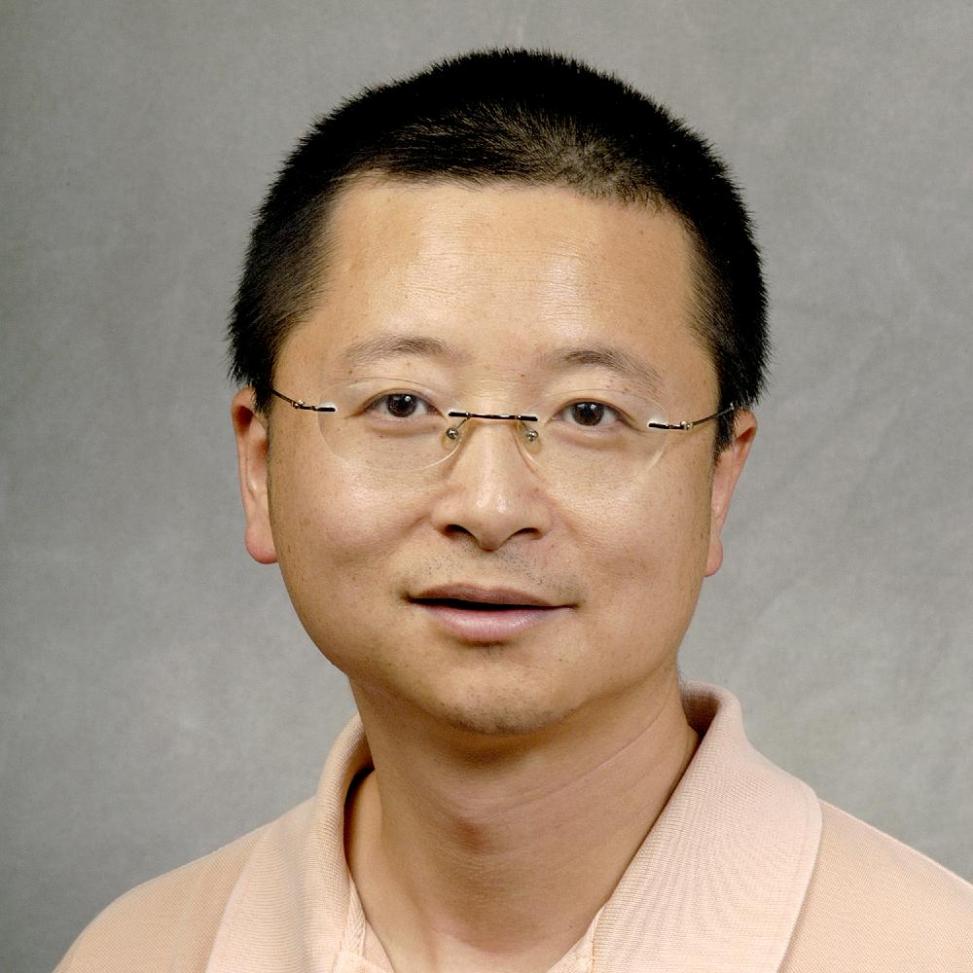
SPEAKER:Tong Yao(爱荷华大学 金融学教授)
TIME/DATE:2026.11.6 12:00-13:00
CLASSROOM:A403
TENCENT:402803862
PW:262914
LINK:https://meeting.tencent.com/dm/tYxeQ1n1xU9L
Abstract:
This study documents a novel finding: fundamental volatility measured using financial statement variables negatively predicts stock returns, an effect that is strikingly pervasive (across a large number of accounting variables that represent operating inputs) and persistent (predicting returns over at least two years). A long-short value-weighted portfolio based on fundamental volatility generates a significantly positive return of 0.93% per month and significant alphas under a variety of factor models including the Fama-French five-factor model and the q-factor model. We use a simple production-based asset pricing model to explain this high-volatility/low-return phenomenon. In the model, due to diminishing marginal return to input, firms with higher operating volatility have lower expected profitability and lower expected stock returns. Further empirical analyses confirm the key predictions of the model that the effect of fundamental volatility on stock returns is mainly through the profitability channel, and that the fundamental volatility effect on both profitability and return is stronger for firms facing more severe diminishing marginal returns in their operations.
GUEST BIO:
Tong Yao is the Keith L. Cook Professor of Finance at the Tippie College of Business, University of Iowa. He received his BA in International Economics from Fudan University in 1991 and his PhD in Finance from Boston College in 2001. Prior to joining the University of Iowa, he was on the faculty of the Eller College of Management at the University of Arizona. He served as a Visiting Financial Economist at the U.S. Securities and Exchange Commission from 2018 to 2019. His research focuses on asset pricing, market anomalies, and investment management by institutional investors such as mutual funds, pension funds, and insurance companies. His work has been published in the Journal of Financial Economics, Review of Financial Studies, Management Science, Journal of Financial and Quantitative Analysis, Journal of Accounting Research, and Review of Asset Pricing Studies, among others. He has served on the editorial boards of Financial Review and China Accounting and Finance Review. He has also worked for or consulted with China Investment Corporation, Numeric Investors, and Bank of Communications. His honors include a Best Paper Award from Financial Review, the Tippie College of Business Research Impact Award, and the First Prize of the INQUIRE Europe Annual Research Award.
ADD:Tongji Building A, Siping Road 1500, SHANGHAI 200092
TEL:0086-21-65983943
FAX:0086-21-65986304
Quick Links:Tongji UniversityMMBSMBSCWRXLRI
We protect your privacy. We use cookies to personalize content, provide features, and analyze traffic to our website anonymously and in a privacy compliant manner. By law, we may store cookies on your device if they are strictly necessary for the operation of this site. For all other cookie types, we need your permission. For more information, please see the privacy policy linked below.

