
Wei Feng: Tea Beverage Brands Tap Ice Cream to Explore New Growth Opportunities
Tue, Oct 13, 2026
Which ice cream shops were the most popular this summer? HEYTEA, CHAGEE, MIXUE, Nayuki and many other tea beverage brands have rushed into the ice cream segment. Wait times at some new stores exceeded three hours. Why have tea beverage brands collectively ramped up investment in ice cream? Recently, Professor Wei Feng from the School of Economics and Management, Tongji University was interviewed by Jiefang Daily. He offered professional insights into this cross-industry boom in the tea beverage sector and discussed whether it can serve as a starting point for companies to pursue new revenue growth. Below is an excerpt from the published article.
Source:Jiefang Daily
The most talked-about ice cream shops this summer surprisingly belong to the tea beverage industry.
On July 24, HEYTEA opened Shanghai’s first Fried Ice Lab store at Shanghai IFC, its third outlet nationwide selling fried ice products. At peak hours after launch, customers waited more than three hours to enter the new store. CHAGEE, another leading tea beverage brand, rolled out its Italian-style gelato series “Cha-lato” at its Wukang Road store in Shanghai back in May. At one point, queues stretched for hundreds of meters as visitors eager to try the new offering lined up outside.
In addition, MIXUE, Nayuki and other tea beverage brands all entered the ice cream market this summer. Behind this collective cross-industry push lies a shared ambition for growth. As the new-style tea beverage market nears saturation and room for innovation in regular drinks hits a ceiling, brands must carve out new growth curves to hold market share and avoid being weeded out amid fierce competition.
The Industry Enters an In-Depth Development Phase
What drives tea beverage brands to embrace ice cream? The core catalyst is mounting pressure across the sector. Amid slowing overall growth, tea beverage operators are desperate to find new revenue sources.
According to the 2025–2030 China New-Style Tea Beverage Market Comprehensive Assessment and Investment Prospect Report, the sector registered year-on-year growth of 5% to 7% in the first three quarters of 2025, far lower than the 24.9% compound annual growth rate recorded between 2017 and 2022. The era of explosive growth has come to an end.
Leading brands are under particularly heavy pressure. Nayuki, known as “the first listed new-style tea beverage company,” posted revenue of 4.331 billion yuan in 2025, a year-on-year drop of 12%. It closed a net of 152 stores over the year, marking its first decline in store count since its IPO. Its market value plunged 96.62% over five years of public trading, erasing more than HK$32.4 billion in market value.
Professor Wei Feng from the School of Economics and Management, Tongji University, notes that while the tea beverage market still has room to expand, supply growth has outpaced demand growth on a macro level, and nearly all companies in the industry are feeling the sharp slowdown.
According to the classic Industry Life Cycle Theory in industrial economics, every industry goes through four stages: introduction, growth, maturity and decline. Over the past decade, the fast-expanding tea beverage sector enjoyed its growth phase. Now, with nearly all potential consumers reached, the market is approaching saturation and transitioning from growth to maturity.
“This means the tea beverage industry has entered a stage of in-depth development,” Wei Feng said. Many current strategies by tea beverage companies essentially seek to unlock new consumption demand from existing customers, and ice cream is a naturally suitable segment to enter.
First, ice cream and tea beverages share largely overlapping customer groups, mainly young people aged 15 to 35. They also align closely in consumption motivations and scenarios: city-center shopping sprees, office afternoon tea, campus leisure, post-meal desserts and summer refreshment, among others. Brands’ massive existing member bases can be converted almost directly into target customers for ice cream products.
Second, ice cream and tea beverages draw on highly similar raw materials and supply chains, keeping adjustment costs low. Major tea beverage brands already operate mature cold-chain logistics systems, so they do not need to build supply chains from scratch to enter the ice cream market, nor do they need to bear steep trial-and-error costs for raw material procurement. Stores only need standard ice cream machines or ice cream roll machines to serve products, without installing complex new equipment.
This “category synergy” — expanding revenue boundaries without materially raising marginal costs — underpins the business logic for many tea beverage brands chasing a second growth curve.
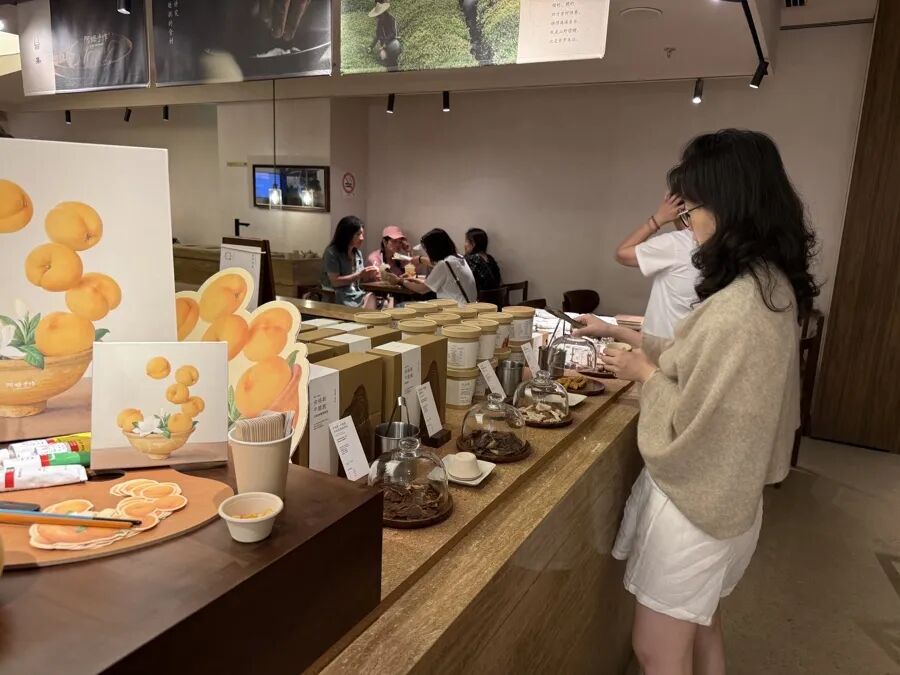
Beyond ice cream, major tea beverage brands have also rolled out adjacent offerings including light meals, snacks and prepackaged gifts. For example, CHA OF YULIAN, positioned around traditional Chinese old-style tea, has launched preserved plums and other classic candied fruits. Guizhou-based brand GoTeaHill has developed Guizhou-style potato chips and Tongren matcha products featuring local ingredients. At its “Home Taste · Market” concept store, AHMA HANDMADEA offers yellow peach gift boxes, Angus beef crisps and other fruit-based and snack products.
“Brands attract foot traffic centered on tea drinks, then extend into matching snacks and desserts aligned with consumption scenarios. They turn a one-off tea purchase into an integrated ‘tea + pastries’ experience”, Wei Feng explained. “At its core, this is ecosystem expansion built around tea-drinking scenarios to increase average transaction value.
Cross-Border Expansion Is a Double-Edged Sword
Can tea beverage brands succeed as they branch into ice cream or snacks?
In the short term, these new products have delivered an immediate boost to tea brands facing sluggish growth. Both HEYTEA and CHAGEE saw strong online buzz and a notable rise in in-store visits after launching ice cream, with foot traffic rising notably at outlets in core commercial districts. Still, the current ice cream boom is highly circumstantial: it benefits from natural summer demand for cold treats, plus the novelty factor that draws early adopters. The real test for these new product lines will come once summer ends and consumer curiosity fades.
The most direct challenge is that ice cream, snacks and other new categories that tea brands are entering represent mature, fiercely competitive markets with established structures—there are no blue ocean markets. As late entrants, tea beverage brands face pressure from competitors across multiple tiers.
Take ice cream as an example. China’s ice cream market is large and stable, dominated by existing players. Industry statistics put its market size at 210 billion yuan in 2025, and it is projected to exceed 220 billion yuan in 2026, though growth is expected to slow markedly. This market has also shifted from competition for new users to a battle over existing customers.
The competitive landscape spans all tiers. In the packaged ice cream segment, established cold drink giants such as Yili, Mengniu and Wall’s dominate supermarkets, convenience stores and community retail channels. For freshly made ice cream, specialty chains like DQ have built solid brand recognition and loyal customers over years of operation. Among emerging local brands, Mr. Savage has grown into a chain with over 1,000 stores. It is clearly difficult for tea beverage brands entering this space to stand out.
Furthermore, it remains to be seen whether new offerings can truly create synergies with core tea products. Economic theory classifies products into complements and substitutes. Complementary products have interdependent demand: higher demand for one lifts demand for the other, such as cars and gasoline. Substitute products compete for the same consumer demand: higher demand for one cuts demand for the other, such as beef and mutton. From this perspective, tea beverages and snacks or preserved fruits can be viewed as somewhat complementary, yet tea, fruit and ice cream may carry substitution risks.
Wei Feng argues that cross-border expansion is a double-edged sword. Done well, new cross-category products can attract new customers: casual shoppers with little interest in a brand’s milk tea may step into the store for an ice cream, bringing incremental foot traffic. If a tea company lacks the operational capacity to support its new business, however, the strategy may backfire. Consumers may grow confused about a brand’s identity, diluting its image and eroding its original core strengths.
Operational Capacity Is the Decisive Factor
In Wei Feng’s view, as the tea beverage market stabilizes and brand rankings largely settle, the coming fierce competition will truly test companies’ comprehensive operational capabilities.
“This set of capabilities differs greatly from what was required during the sector’s high-growth era. Back then, brands could rise rapidly by opening stores aggressively and pouring capital into market expansion. Today, competition has shifted to refined management, including in-store quality control, reputation maintenance, cost control across upstream and downstream supply chains, and negotiation leverage with platform partners. Weakness in any link can become a fatal bottleneck.” Wei Feng says brands must identify their niche and define a clear profit model. “They can either dig deep in a niche market and build supply chain barriers, or develop unique, irreplaceable features.”
MIXUE exemplifies one successful approach, built around supply-chain-driven expansion. Though its retail prices are low, MIXUE does not primarily profit from retail tea sales. Instead, it positions itself as a supply-chain service provider for its franchise network, earning revenue by supplying raw materials, equipment and brand licensing to franchisees. Supported by this model, MIXUE does not directly operate most front-end retail outlets, yet it has achieved large-scale global expansion through franchising and grown into an industry leader.
Even so, the supply-chain model is not risk-free. Its biggest challenge lies in quality consistency, given that most stores are not directly operated by the brand. “This presents an ongoing test for MIXUE,” Wei Feng notes. The company must keep its management focus on franchisee screening, training and elimination mechanisms, relying on a mature operating system to guarantee uniform product quality across all outlets.
The alternative path to the supply-chain strategy centers on end-consumer markets. Brands with strong offline marketing and customer operations expertise tend to keep leaning into front-end product development and promotion. Yet as the industry matures and traffic-driven growth fades, it has become far harder to create market sensations with a single hit product. New-product marketing and paid traffic deliver diminishing marginal returns, and marketing alone cannot sustain long-term breakthroughs.
Wei Feng states that for the tea beverage industry, branching into ice cream, snacks and other categories is merely a starting point for exploring new growth — not the destination. “Companies must keep refining their operational capabilities and management sophistication, backed by robust supply chains, standardized quality control and viable profit models. Only then can cross-category ecosystems turn into lasting growth momentum and evolve into a genuine second growth curve.”
(Source: Jiefang Daily, August 10, 2026)
ADD:Tongji Building A, Siping Road 1500, SHANGHAI 200092
TEL:0086-21-65983943
FAX:0086-21-65986304
Quick Links:Tongji UniversityMMBSMBSCWRXLRI
We protect your privacy. We use cookies to personalize content, provide features, and analyze traffic to our website anonymously and in a privacy compliant manner. By law, we may store cookies on your device if they are strictly necessary for the operation of this site. For all other cookie types, we need your permission. For more information, please see the privacy policy linked below.

